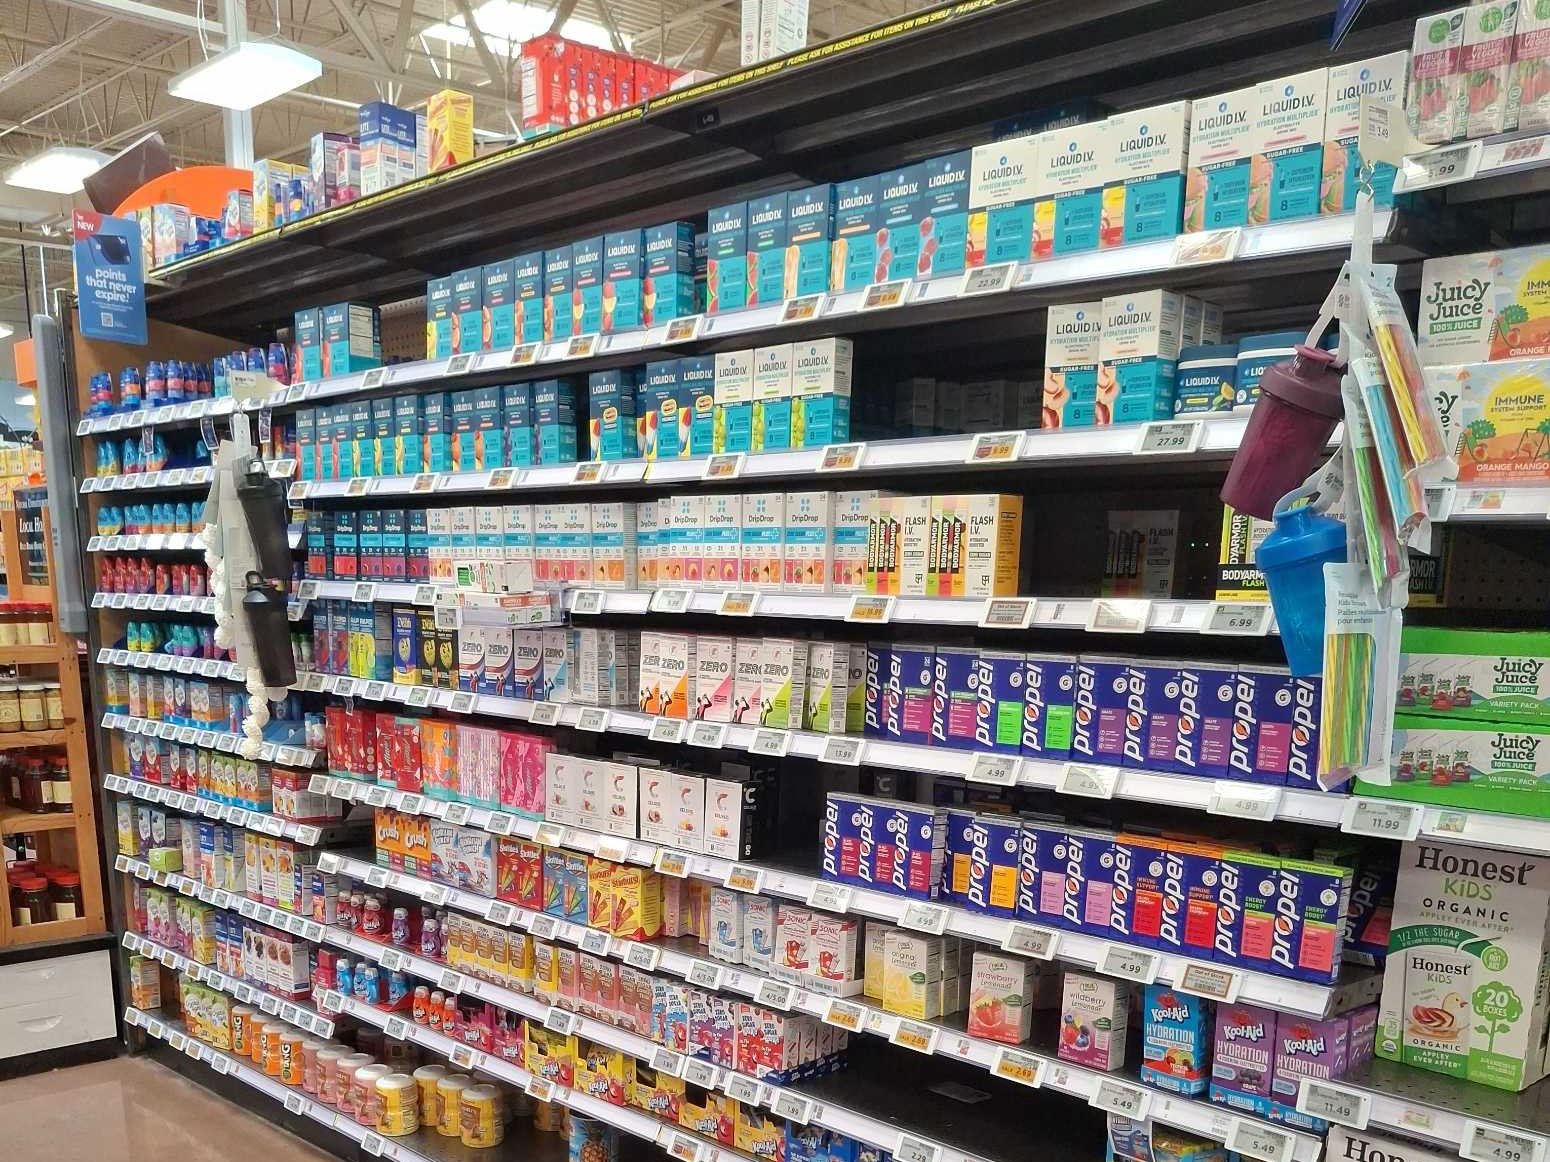
We checked the hydration stick aisle at Target, CVS, Kroger, Albertsons, Publix and H-E-B stores across 30+ US states between October 27 and November 9, 2026. Liquid I.V. was on the shelf in 98% of stores. The section is small and often incomplete: 75% of stores had at least one out-of-stock on the shelf. In-store visibility is rare: a shelf talker in 13% of stores, a secondary display in 18%.
Liquid I.V. Is Almost Everywhere
Share of stores where each brand is on the shelf
Source: Roamler Hydration Shelf Check, US stores, Oct 27 to Nov 9, 2026
Liquid I.V. is on the shelf in 98% of stores, followed by Propel (85%) and Gatorade Zero (77%). For the other brands, presence depends heavily on the retailer. Celsius is in 84% of Target stores and 89% of Albertsons stores, but almost absent from Publix and H-E-B.
Store brands are on the shelf in 70% of Albertsons stores and 66% of CVS stores, but in only 16% of Target stores and in no Publix store.
Some brands rely on one retailer. Pedialyte is in 70% of CVS stores and in every H-E-B store, but rare elsewhere. DripDrop is in 83% of Kroger group stores.
A Growing Category
In 64% of stores, the section fits in a single bay. That’s true in almost every Target store. The widest sections are in the Kroger group (1.7 bays on average) and at H-E-B (1.9).
Out-of-Stocks in 3 of 4 Stores
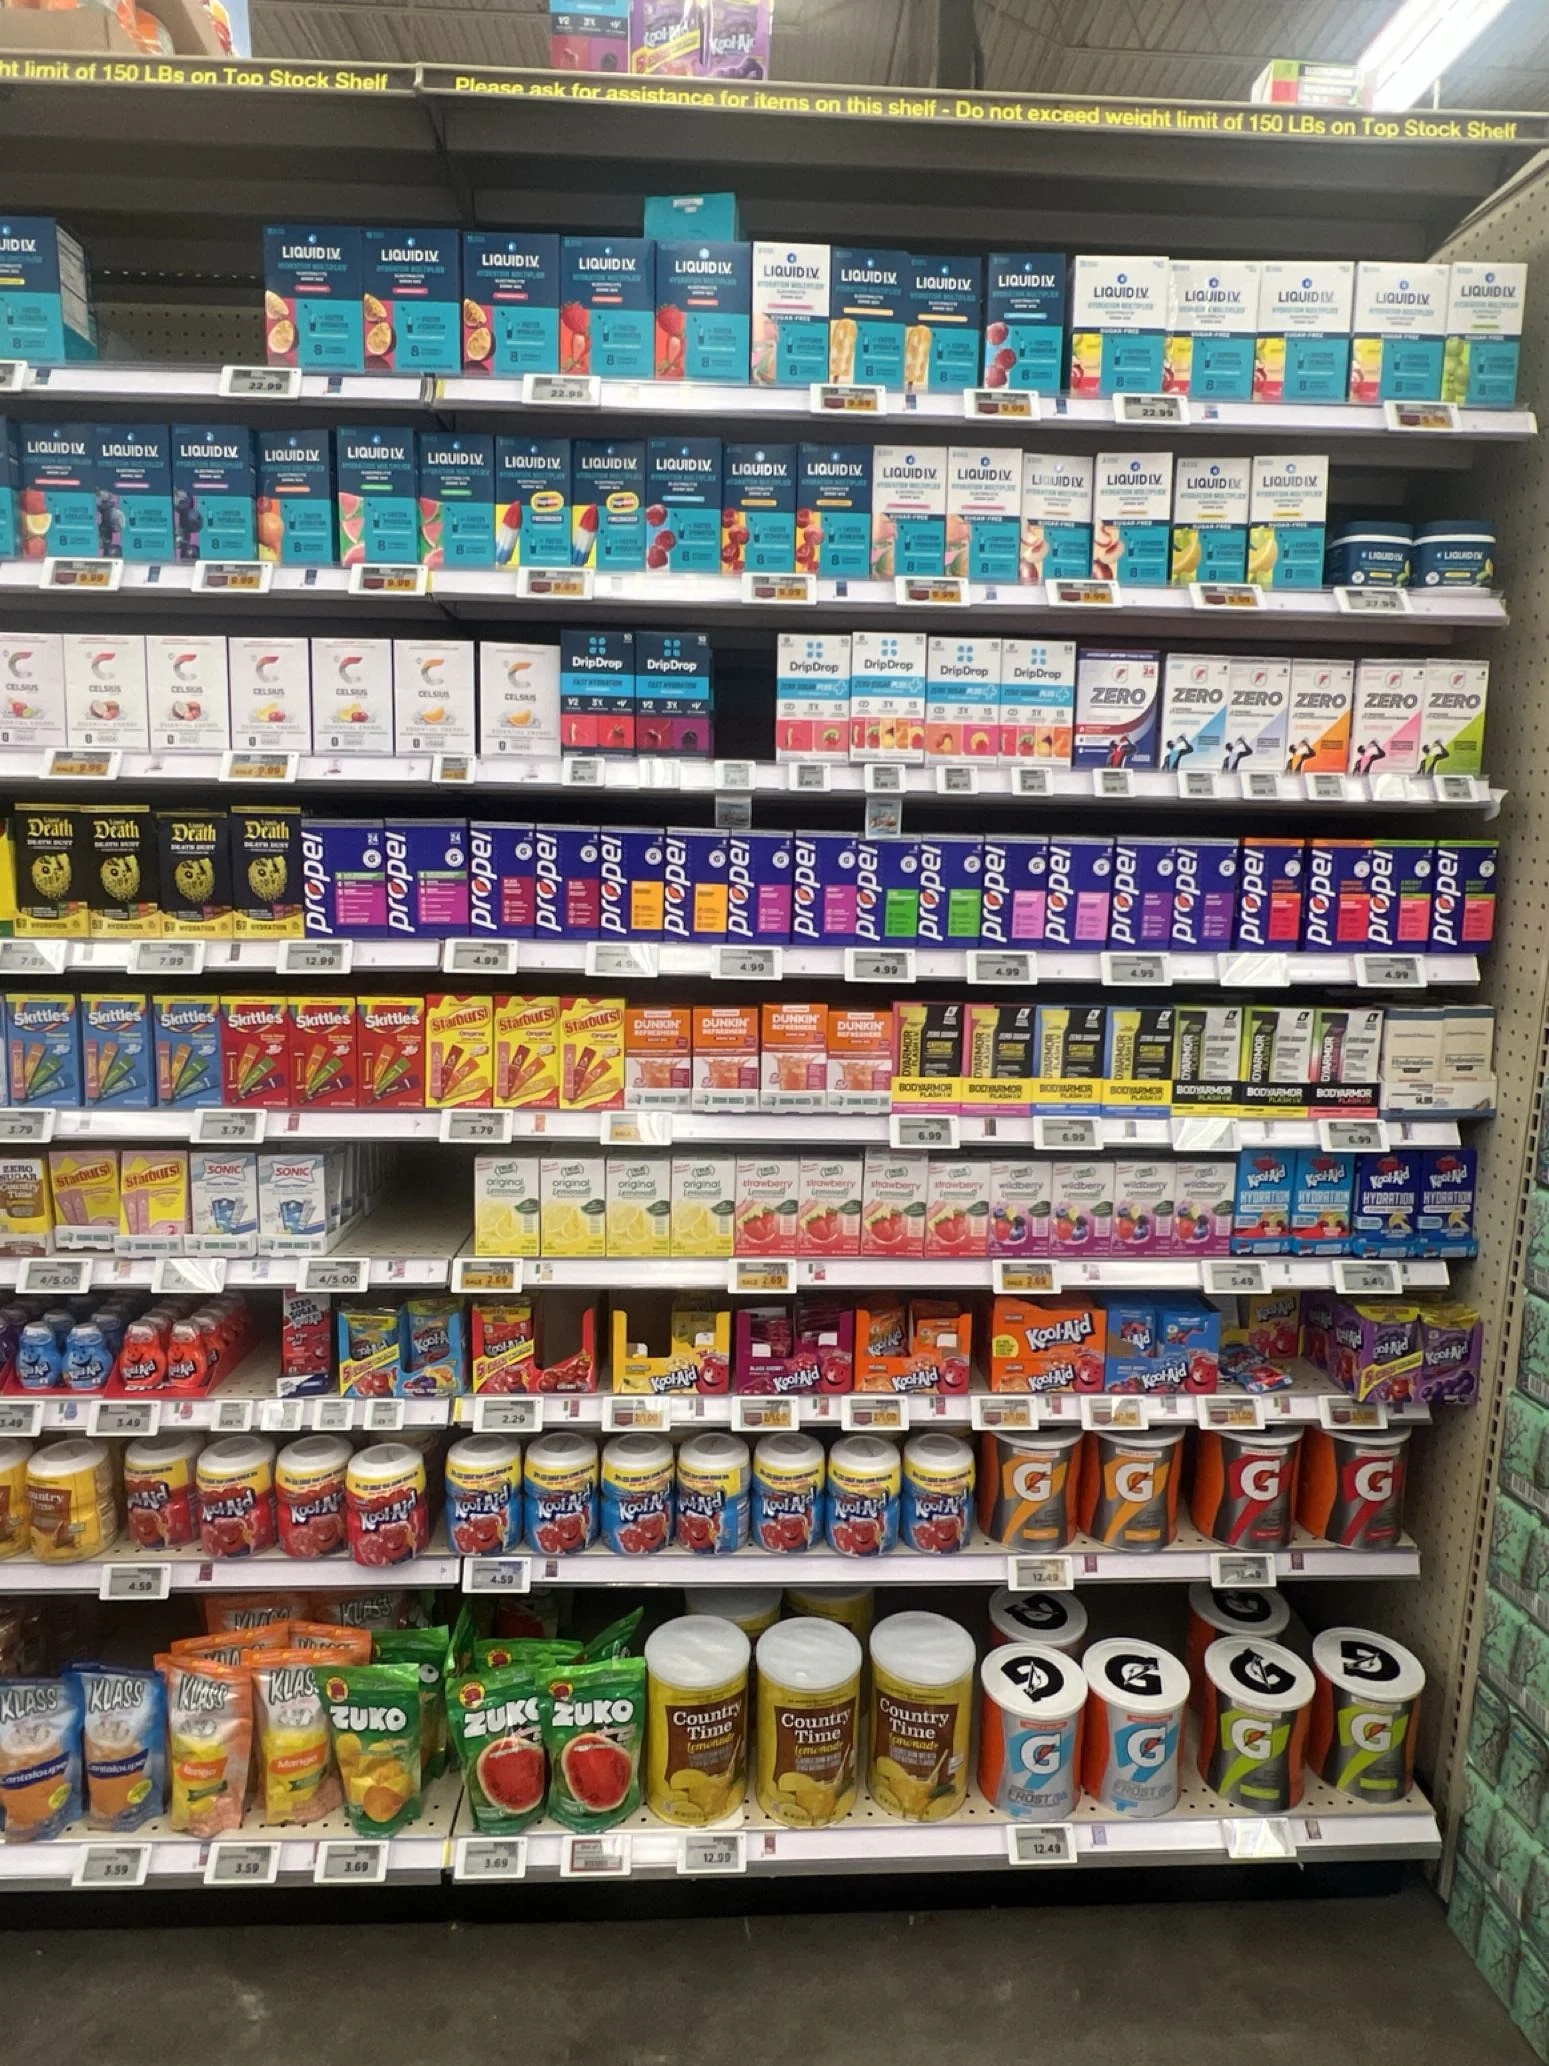
75% of stores had at least one out-of-stock on the shelf, meaning a price tag with no product behind it. Stores had 2.6 out-of-stocks on average, and 18% had five or more. Every retailer is affected: at each one, more than 60% of stores had at least one out-of-stock.
Minimal In-Store Execution
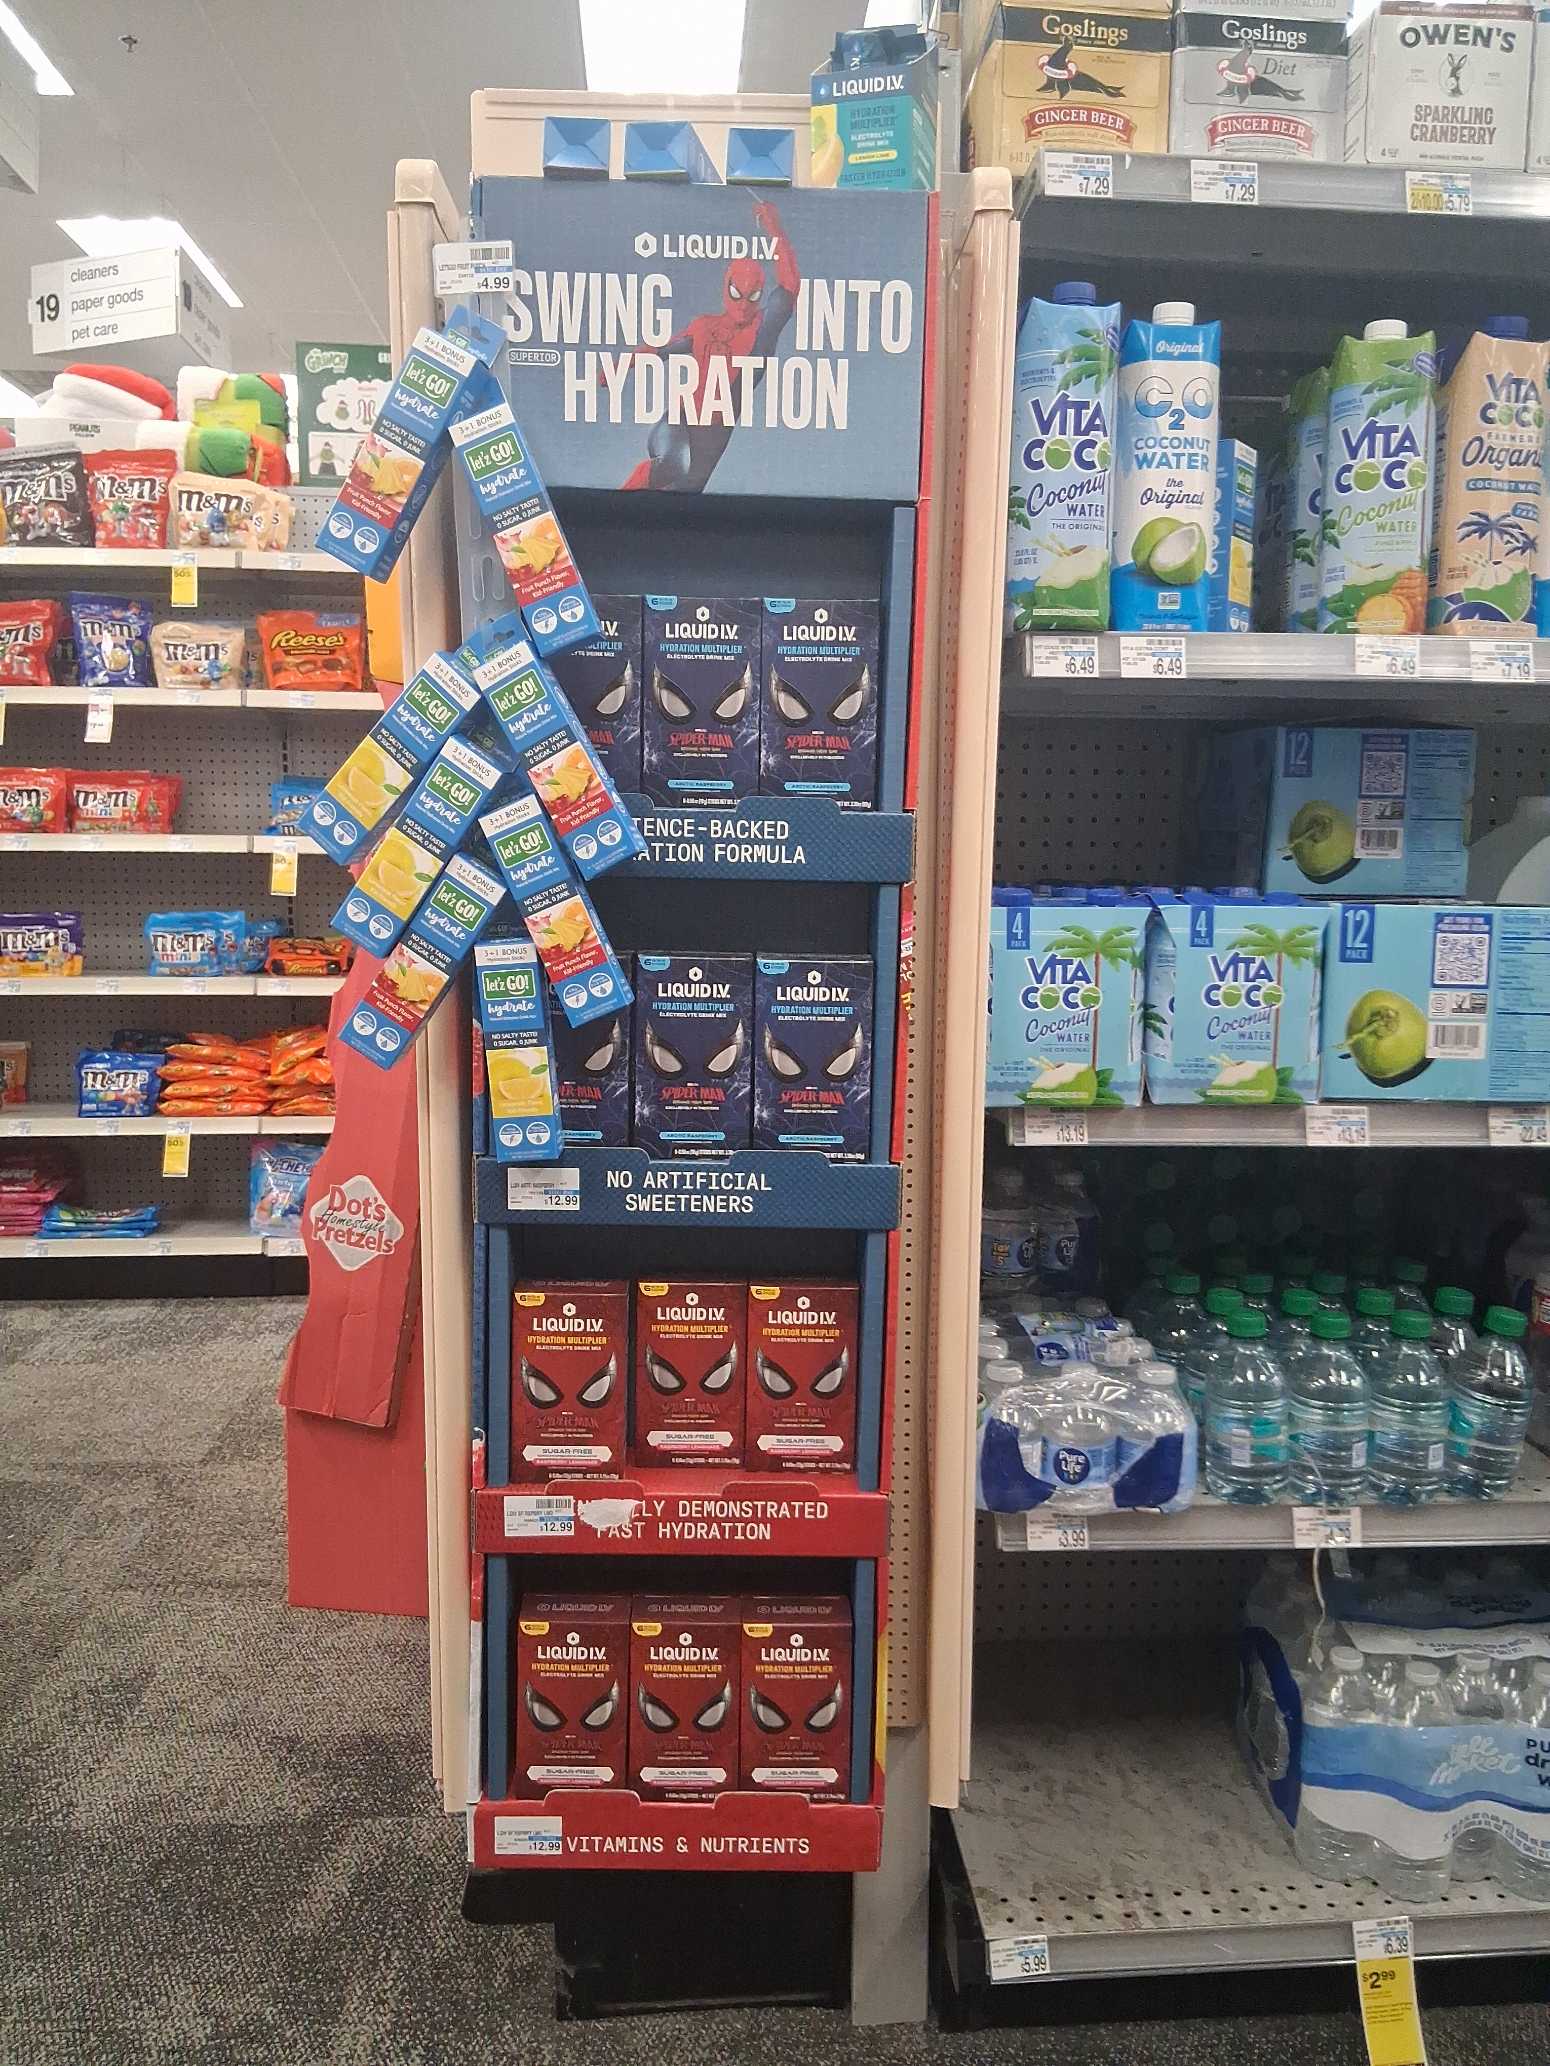
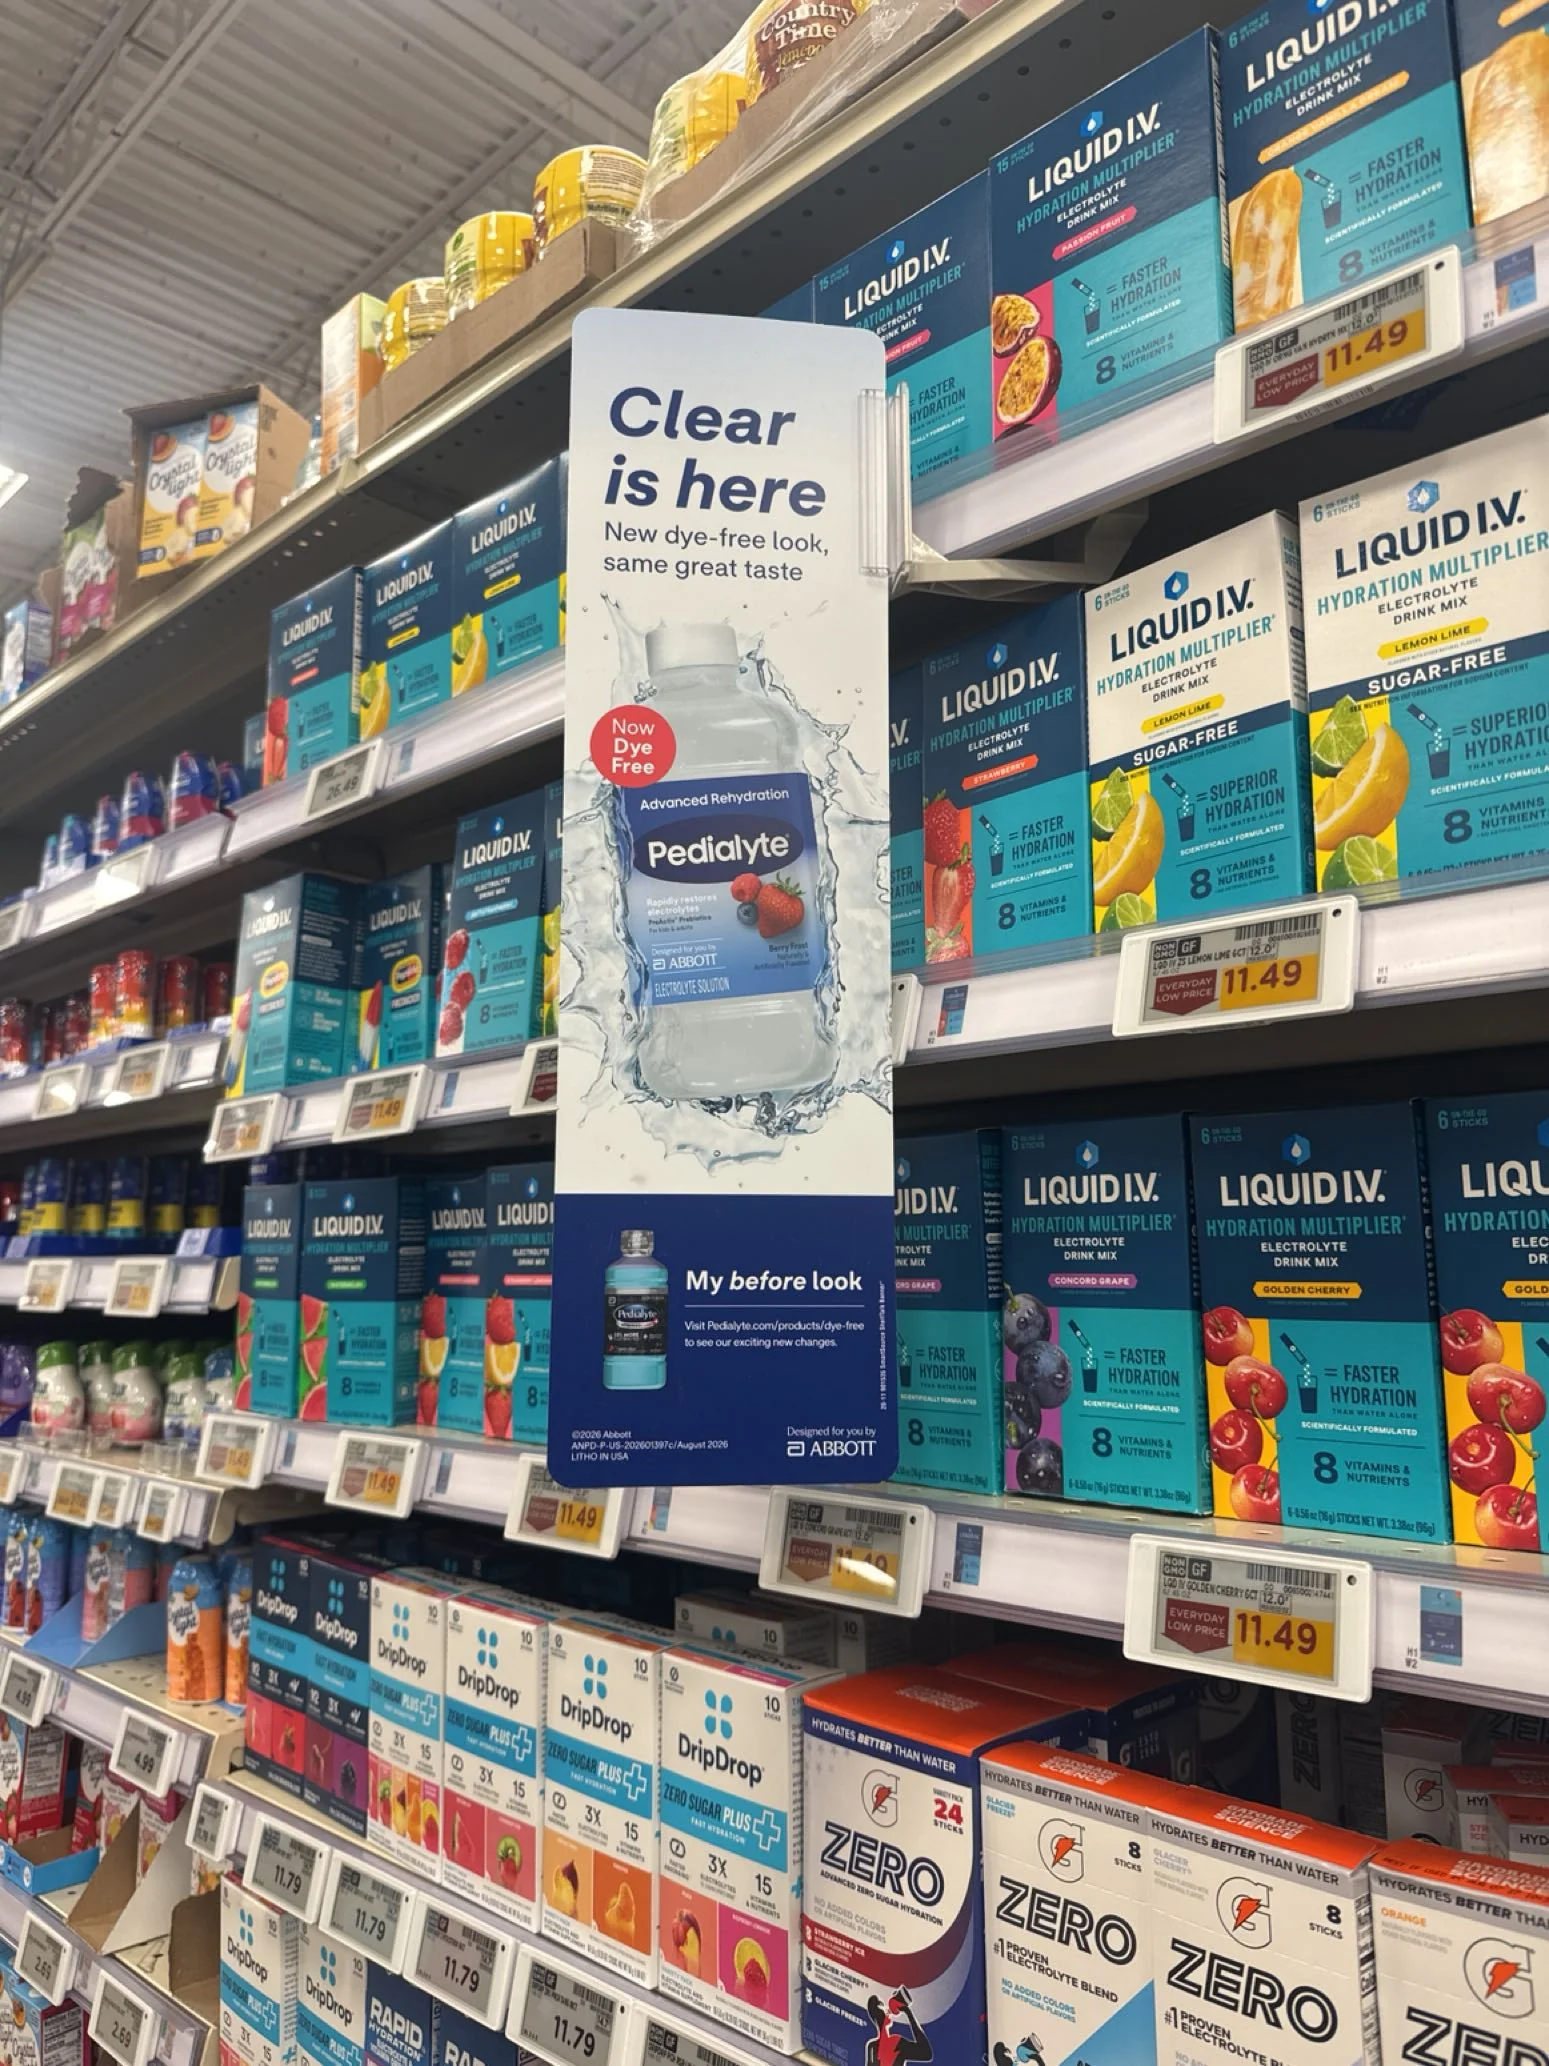
A shelf talker was on the section in 13% of stores. A secondary display (endcap, next to water cases, near the checkout cooler) was in 18% of stores.
Target and CVS account for most secondary displays (26% and 29% of their stores). In Kroger, Albertsons and Publix supermarkets, they are rare (8% of stores or fewer).
New Brands Are Coming In
In 60% of stores, we found at least one brand outside the 18 we tracked. Cure is the most common: it’s in 26% of stores, and in about half of Target and Albertsons stores.
DryWater is in 13% of stores, mostly at Target (41%). G Fuel appears in 9% of stores, all of them CVS.
What Shoppers Would Buy
We also asked each Roamler which brand they would buy from the shelf in front of them. Liquid I.V. came first, picked by 35% of respondents. The main reason given was flavor, named by more than half of those who picked a brand. Packaging came next (38%), then price and already being a user (30% each). Seeing advertising came last (11%).
Reasons given by Roamlers who picked a brand (several answers possible)
Source: Roamler Hydration Shelf Check, US stores, Oct 27 to Nov 9, 2026
What This Means for Brands
- Availability has to be checked store by store. Three in four stores have at least one out-of-stock on the shelf. Since the section often fits in a single bay, every empty price tag stands out.
- A national average hides gaps between retailers. Celsius is strong at Target and almost absent at Publix. Store brands carry weight at Albertsons and CVS, much less at Target. Brands need to track their presence retailer by retailer.
- There is room for more in-store visibility. With a shelf talker in 13% of stores and a secondary display in 18%, a brand that invests in in-store visibility faces little direct competition.
- New brands often start with one retailer. Cure and DryWater are mostly at Target, G Fuel at CVS. For a new brand, the first months at a retailer are when it matters most to know whether it’s actually on the shelf, and where.
How is your brand showing up on US shelves?
In a rapidly evolving and growing category like this one, it’s important to have eyes on the shelves. With Roamler, you can run a category check like this in any category, in just the stores that matter to you. If you need a sample or a recurring view of your category, reach out.
Talk to us about your projectMethodology
We visited 211 stores across six retailers and 30+ US states between October 27 and November 9, 2026, with one check per store. The six retailers were Target, CVS, Kroger and its regional banners, Albertsons and its regional banners, Publix and H-E-B.
The check covers hydration sticks in the broad sense: single-serve powder sticks or pouches you mix into a glass or bottle of water, with a functional benefit (hydration, energy or protein). Store brands are included. Flavor-only mixes, liquid water enhancers, multi-serve tubs and ready-to-drink products are not.
In each store, a Roamler photographed the storefront, the full aisle and every bay in the section, and recorded:
- the brands on the shelf, from a list of 18, plus store brands and any other brand they found;
- the number of bays the section takes up;
- out-of-stocks on the shelf, meaning price tags with no product behind them, with a photo of each one;
- shelf talkers and secondary displays (outside the regular shelf), with a photo of each;
- which brand they would buy, and why.
Every check was verified from the photos before it went into the results.